Home Insurance in Ireland
An independent guide to home insurance in Ireland: buildings versus contents, rebuild cost versus market value, underinsurance, excesses and exclusions, and what to prepare before you compare cover, plus a free Home Insurance Check.
The comparison service is provided on CompareInsuranceIreland.ie.
What this guide covers
Home insurance decisions are easy to get wrong in ways that only become obvious when you make a claim. This guide sets out what buildings and contents cover actually protect, how to work out realistic figures for each, which policy terms deserve close attention, and which changes to your home or circumstances your insurer needs to know about. It also sets out what to have ready before you compare cover.
Buildings cover and contents cover are different things
Most home insurance confusion starts with treating "home insurance" as one product. It is usually two, and which you need depends on whether you own or rent.
- Buildings insurance. Covers the structure of your home and anything you would not take with you if you moved out: walls, roof, floors, fitted kitchens and bathrooms, and permanent outbuildings. This is what a mortgage lender requires cover for.
- Contents insurance. Covers what you would take with you: furniture, appliances, electronics, clothing and personal belongings. A tenant typically only needs contents cover, since a landlord is responsible for insuring the building itself.
- Combined policies. Most owner-occupiers buy buildings and contents together as a single combined policy, but the two sums insured are still calculated separately and each needs to be realistic on its own terms.
Rebuild cost, not market value, is what you insure
The single most common mistake in buildings insurance is using a home's market value, or its purchase price, as the sum insured. Market value includes the site and its location, neither of which needs to be rebuilt after a fire, storm or flood. What actually needs insuring is the cost to demolish the damaged structure and rebuild it to the same specification, plus professional fees and site clearance.
The Society of Chartered Surveyors Ireland publishes a rebuild cost calculator that gives a base estimate for standard estate-type houses built from the 1960s onwards. It does not cover period, bespoke, thatched or basement properties, houses of more than three storeys, or apartments, and it is a starting estimate rather than a substitute for a professional valuation on an unusual property.
A house bought for €420,000 might have a genuine rebuild cost closer to €300,000, since the site and location, which make up much of the purchase price, are not part of what insurance needs to replace. Insuring for the purchase price alone can mean paying for cover you do not need, or in the reverse case, insuring an older or larger property for less than it would actually cost to rebuild.
Underinsurance and the average clause
If your buildings sum insured is lower than the true rebuild cost, most Irish policies apply what is known as an average clause. Rather than simply running out of cover once the shortfall is reached, the clause reduces every claim payout by the same proportion as the underinsurance, including on a partial claim.
If your home's true rebuild cost is €300,000 but you have insured it for €225,000, you are insured for 75% of its value. A claim for a €20,000 roof repair could then be settled at 75%, or €15,000, not the full cost of the repair. The shortfall applies across every claim on the policy, not just to a total loss.
The way to avoid this is straightforward: use a proper rebuild cost estimate, not a guess or a market value figure, and review it again after any extension or major renovation. If a claim is ever disputed on underinsurance grounds, the Financial Services and Pensions Ombudsman can examine whether the insurer's question was clear and your answer reasonable at the time.
Choosing a realistic contents sum insured
Contents cover can be underinsured as easily as buildings cover. To estimate it realistically, walk through each room and calculate what it would cost to replace everything with new equivalents, rather than what the items are worth second hand.
Policies also set a single item limit, which is the most paid for one item unless it is listed separately. Limits vary, so check your policy. Jewellery, art, bicycles and electronics above the limit may need to be declared and valued separately.
If you regularly take belongings away from home, such as a laptop or hobby equipment, check whether your policy includes cover outside the property.
Accidental damage, excesses and exclusions to check
Two policies with a similar price can differ significantly in what they actually pay out. These are the terms worth comparing line by line rather than assuming they are the same.
Flood, storm, subsidence and escape of water
These four risks are usually included in standard buildings cover, but insurers assess and price each of them differently depending on your specific property, so it is worth understanding what affects them before you compare quotes.
- Flood risk. The Office of Public Works publishes national flood maps at Floodinfo.ie. Insurers use their own flood modelling for underwriting rather than the OPW maps directly, but Insurance Ireland members have committed to taking completed OPW flood defence schemes into account.
- Subsidence. Ground movement affecting foundations, often linked to soil type, nearby trees, or a leaking underground pipe. It typically carries a higher excess than other claims.
- Escape of water. One of the most common home insurance claims, covering damage from burst pipes or leaking plumbing. It commonly has its own separate excess, so check that figure.
If your property has a known history of flooding, subsidence or escape-of-water claims, tell your insurer directly rather than relying on a general area-level assessment.
Security conditions, unoccupied homes and working from home
Several common circumstances change what a policy requires, and missing one can affect a claim even where the underlying event would otherwise be covered.
- Security conditions. Some policies require an approved lock standard or a monitored alarm to be active, particularly for higher-value contents. Keeping a listed condition in place matters for any theft claim, not just for a premium discount.
- Unoccupied homes. Most policies restrict cover once a home has been left empty beyond a set number of days. That threshold varies by policy, so check your wording, and tell your insurer in advance of an extended absence, such as a long stay abroad.
- Working from home. Standard contents cover usually includes a limited amount for home office equipment, but a business run from home or client visits can fall outside a standard policy. Tell your insurer so they can confirm what is covered.
Renovations, extensions and structural work
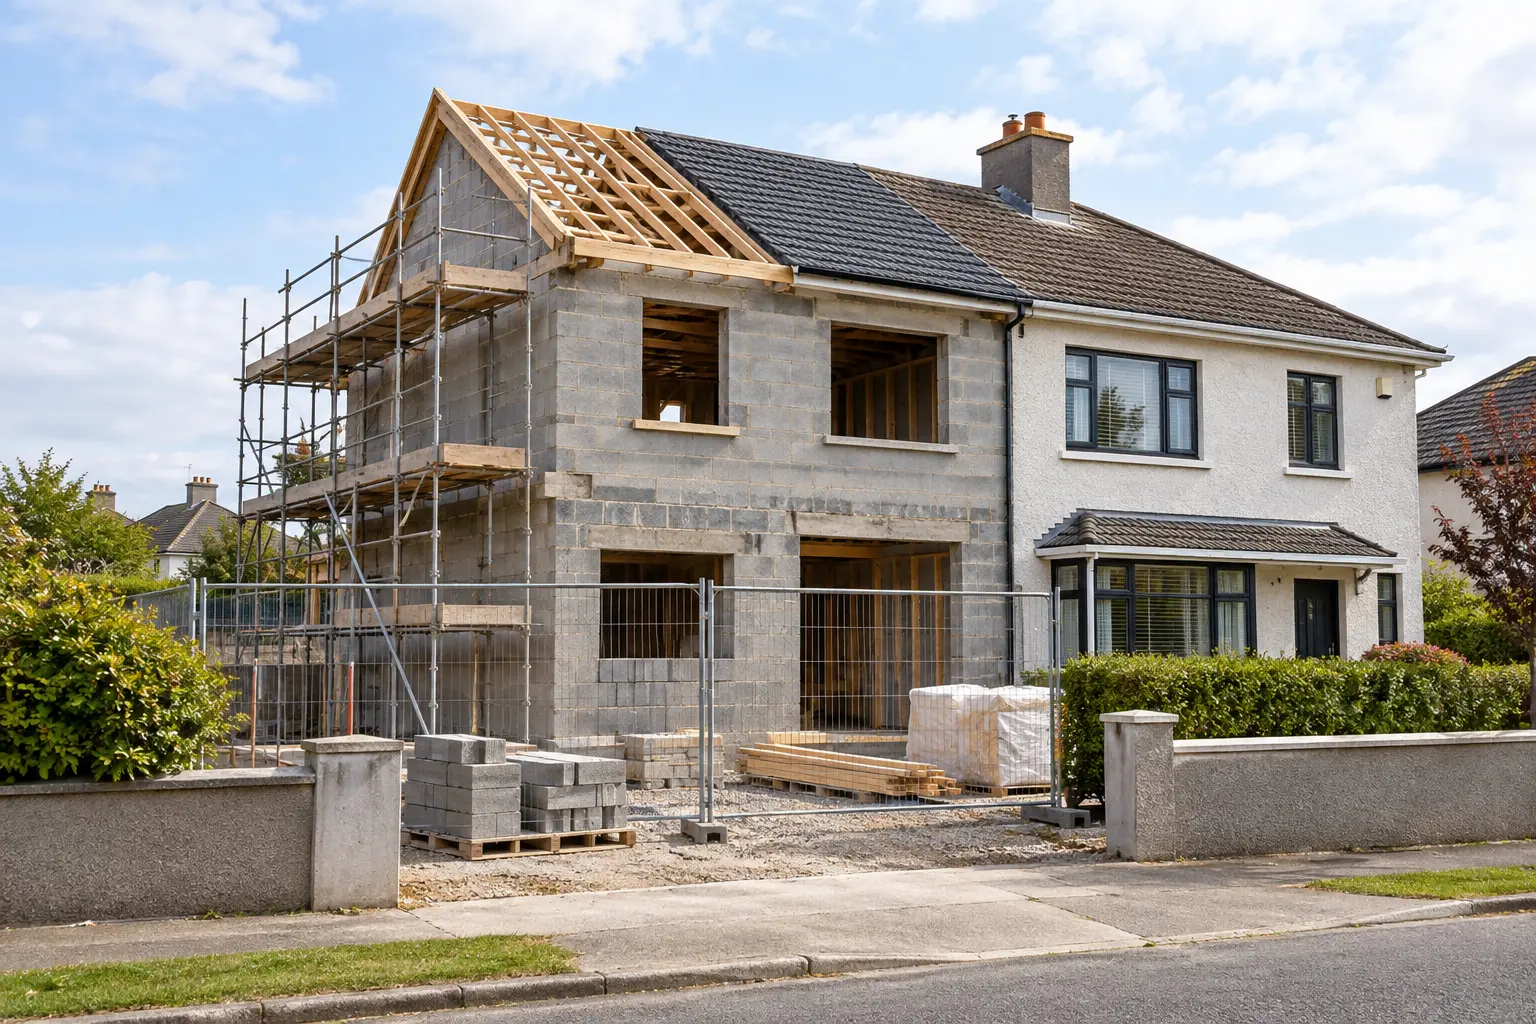
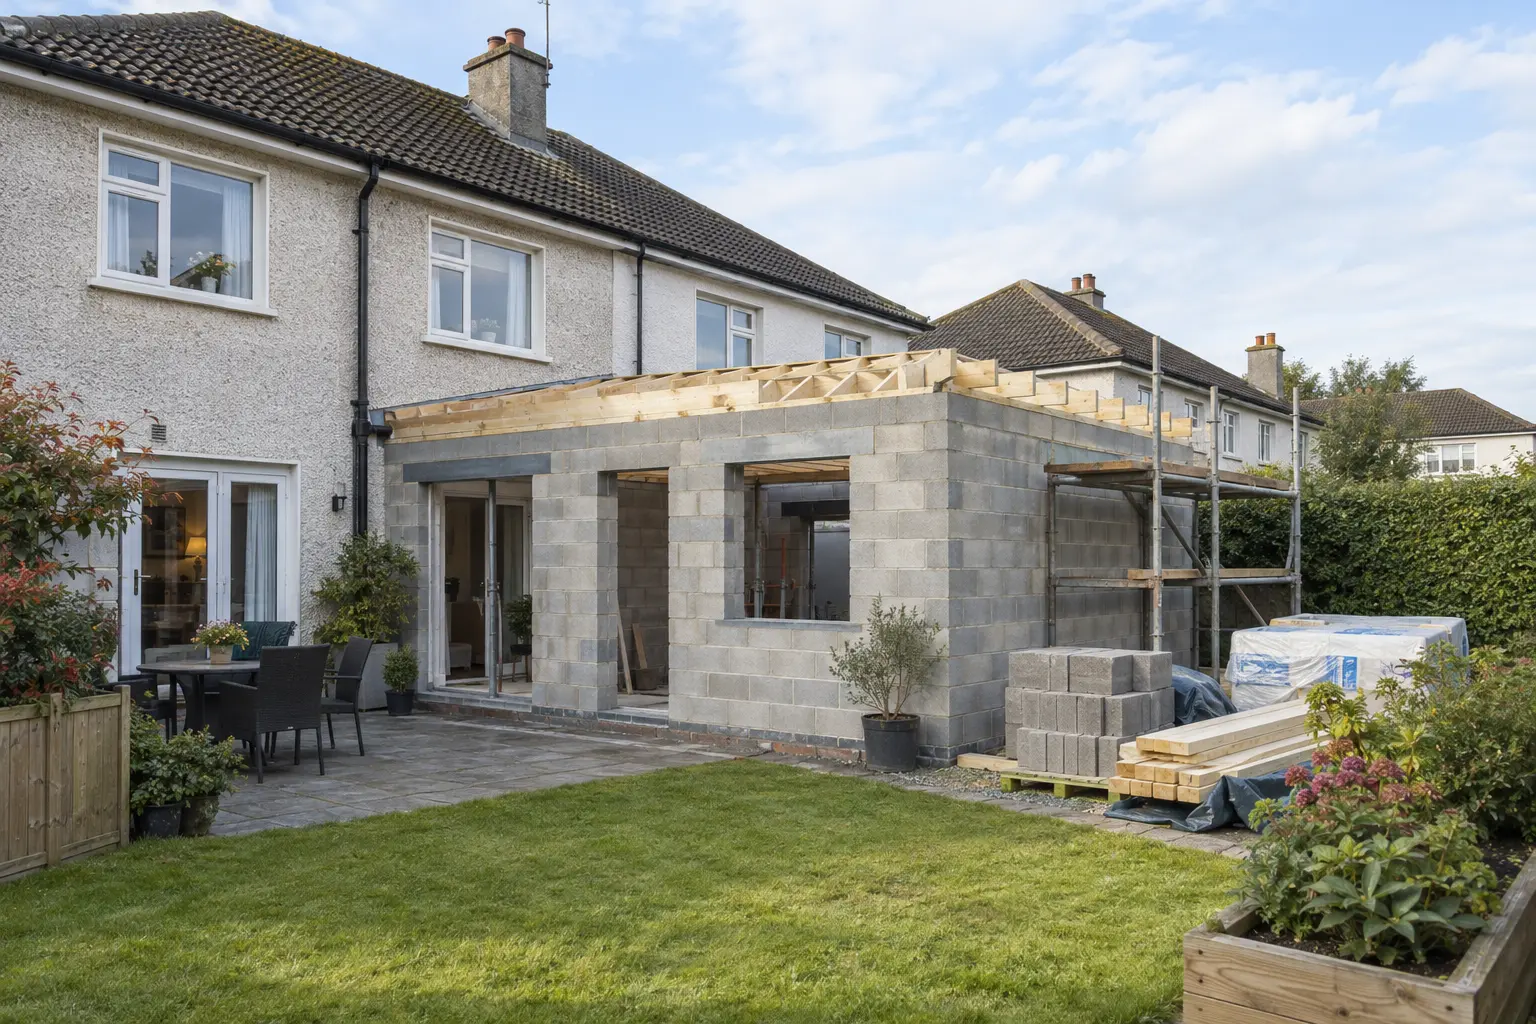
An extension, loft conversion or structural alteration can increase your rebuild cost and temporarily change the risk. Tell your insurer before significant work begins, as standard cover may be restricted or excluded during construction unless the insurer agrees otherwise. Ask what conditions apply to security or occupancy during the work, and check that the contractor has suitable insurance for the project.
If you add a two storey extension without increasing the sum insured, the policy may no longer reflect the home's rebuild cost and the average clause described earlier could apply to a claim. When work is complete, update the rebuild estimate and buildings sum insured. Keep planning permission and completion documents in case the insurer requests them.
Claims history and answering insurer questions accurately
Under the Consumer Insurance Contracts Act 2019, an insurer must ask clear, specific questions, and you must answer them honestly and with reasonable care. You are not required to volunteer information beyond what you are actually asked, but an inaccurate or incomplete answer to a question that was asked can affect a later claim or, in serious cases, the validity of the policy itself.
This applies to renewals as well as new policies: an insurer that wants updated information at renewal, such as recent claims, a change of occupancy, or work done on the property, needs to ask for it specifically. Keep a simple record of any claims made, even ones your previous insurer settled quickly, since you will usually be asked about claims history directly when comparing or renewing cover.
Mortgage lender requirements, renewals and switching
It helps to separate what your lender requires from what the law requires, since the two are often assumed to be the same thing.
Home Insurance Check
Answer a few questions about your home and circumstances to see what deserves particular attention when you compare cover. This tool does not calculate a premium, does not recommend an insurer or policy, and does not state whether any level of cover is sufficient. It is an educational starting point only, not insurance advice.
What to prepare before you compare
- A rebuild cost estimate. From the SCSI calculator for a standard property, or a professional valuation for an older or non-standard one.
- A realistic contents figure. Worked out room by room at new-for-old replacement cost, not secondhand value.
- A list of higher-value items. With approximate values, so you know which items may need to be specified separately.
- Your claims history. Dates and a brief description of any claims made in recent years, even small ones.
- Any circumstances that changed. Renovations, extended vacancy, working from home, or security measures added or removed.
- Your mortgage lender's requirements. If applicable, the minimum buildings sum insured your lender expects to see noted on the policy.
Ready to compare home insurance?
Upgrader.ie provides the information and the preparation on this page. Continue to CompareInsuranceIreland.ie to explore home insurance options.
Compare home insurance at CompareInsuranceIreland.ie (opens in a new tab)You will continue to CompareInsuranceIreland.ie, which is also operated by Magenta Online Marketing.
Upgrader.ie and CompareInsuranceIreland.ie are operated by Magenta Online Marketing. Upgrader.ie is an independent information resource; CompareInsuranceIreland.ie provides the home insurance comparison service. See our Provider & Partnership Disclosure.
Frequently asked questions
Is home insurance a legal requirement in Ireland?
No. Home insurance is not a statutory requirement in Ireland the way third party motor insurance is. A mortgage lender will almost always require buildings cover, though, so it is effectively a condition of most mortgages. See Mortgage lender requirements above.
What is the difference between buildings insurance and contents insurance?
Buildings insurance covers the structure of your home: walls, roof, fitted kitchens and bathrooms, and permanent outbuildings. Contents insurance covers what you would take with you if you moved out. See Buildings cover and contents cover are different things above.
Why is my buildings sum insured not the same as my home's market value?
Market value includes the site and location, neither of which needs to be rebuilt after a fire or storm. Buildings insurance should instead reflect the rebuild cost. See Rebuild cost, not market value, is what you insure above.
What is the average clause and how does underinsurance affect a claim?
If your buildings or contents are insured for less than their true value, most Irish policies apply an average clause, reducing any payout in the same proportion as the shortfall. See Underinsurance and the average clause above.
Do I need to tell my insurer about renovations or an empty property?
Generally yes. Under the Consumer Insurance Contracts Act 2019 you must answer your insurer's questions honestly and with reasonable care, and renovations or an extended vacancy are circumstances insurers commonly ask about. See Renovations, extensions and structural work above.
Does Upgrader.ie compare home insurance policies itself?
No. Upgrader.ie is an independent information resource. CompareInsuranceIreland.ie, also operated by Magenta Online Marketing, provides the home insurance comparison service itself.
Go deeper on a related topic
- Solar Panels in Ireland: suitability, cost, grants, generation and exporting electricity, useful to know before telling your insurer about a solar PV installation.
- Insulation in Ireland: what an insulation upgrade involves and when it counts as work an insurer should be told about.
- Current home energy grants: SEAI grant amounts and eligibility across home upgrades.
- All guides: our full library of independent home upgrade and home services guides.
Where to verify the latest position
This page summarises publicly available guidance current as of September 2026. It is not a substitute for checking directly with the bodies below, and figures, rates and policy terms can change after publication.
- CCPC: Home insurance (opens in a new tab), checked September 2026
- Citizens Information: Types of insurance (opens in a new tab), checked September 2026
- Society of Chartered Surveyors Ireland: House rebuild cost calculator (opens in a new tab), checked September 2026
- Central Bank of Ireland: Consumer Protection Code (opens in a new tab), checked September 2026
- Irish Statute Book: Consumer Insurance Contracts Act 2019 (opens in a new tab), checked September 2026
- Irish Statute Book: Occupiers' Liability Act 1995 (opens in a new tab), checked September 2026
- Floodinfo.ie: Office of Public Works national flood maps (opens in a new tab), checked September 2026
- Financial Services and Pensions Ombudsman (opens in a new tab), checked September 2026
Explore more ways to manage your household bills
Home insurance is one part of your household bills. Browse our other Home Upgrades and Home Services guides to see what else could suit your household.
Explore Home Services